


Economic Warnings in the AI Sector: Insights from Torsten Slok
This past week, Torsten Slok, Chief Economist at Apollo, raised significant alarms regarding the trajectory of the artificial intelligence (AI) sector, coinciding with Wall Street’s cautious stance towards AI investments. His insights highlight concerns about sustainability and profitability in this rapidly evolving technology landscape.
Concerns About Demand and Spending
Slok pointed out a noticeable slowdown in the growth of token spending related to AI technologies. He noted that the demand curve for computational power has flattened and is particularly sensitive to pricing fluctuations. Despite increased investments, many firms have not yet realized substantial productivity gains, leading to a perception that AI is acting more as a cost center rather than a catalyst for growth.
“The core economic flaw in the AI bull case is that the marginal cost of producing compute exceeds the marginal benefit it delivers to users,” Slok stated. This imbalance poses questions regarding the anticipated demand for data centers. He elaborated that the necessary amount of compute power and data centers is contingent upon the returns businesses achieve from these investments, a return that has been slow in materializing, thus contributing to hesitance in spending on AI services.
Pricing and Corporate Reliance on AI
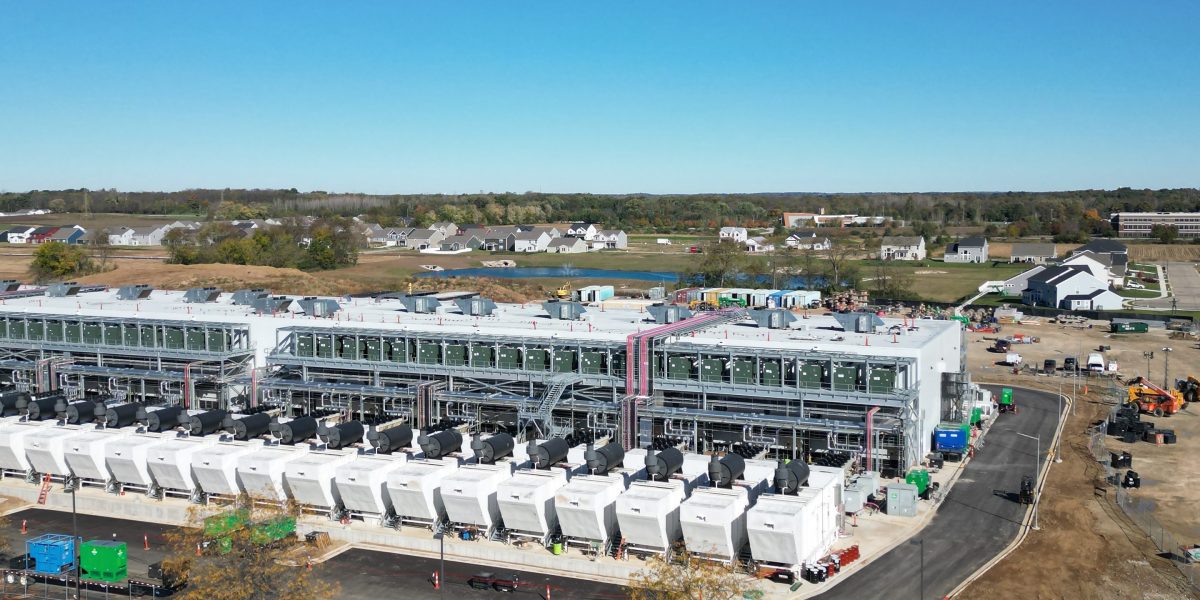
Slok argued that the primary factor influencing data center construction isn’t simply physical capacity, but rather the prices companies are prepared to pay for computational resources. “Companies will only pay a high price if it translates to higher revenue growth, bigger profits, or substantial savings—and there are little signs any of those exist at scale,” he noted, reflecting his skepticism about current AI implementations.
Questions Surrounding Venture Capital Backing
On Thursday, Slok raised concerns regarding the interconnected financial structures involving AI companies, where spending appears circular. A significant percentage—80%—of the most substantial AI spenders are venture capital-backed firms. This observation suggests that many startups are funding their operational costs through external investment rather than via organic earnings, which raises questions about the longevity of their financial models.
The Financial Implications of AI Adoption
Slok’s analysis culminated on Saturday with a forceful declaration that AI has “delivered zero financial payoff” for U.S. corporations, excluding the major tech players. While companies like the Magnificent Seven are seeing improved profit margins and revenue per employee, other firms within the S&P 500 have not experienced similar improvements. He emphasized that AI may not align with all corporate needs and expressed doubt as to whether organizations would be willing to pay for advanced AI services in the future.
“AI may be a great calculator, but in business, intelligence is mostly judgment,” Slok remarked. He articulated that judgment relies on context and varies based on the individual or model consulted. Importantly, he identified that AI lacks comprehension of aspects like accountability, trust, and ethical trade-offs, which are crucial for driving revenue growth and profit margins.
Market Reactions and Future Prospects
Amidst Slok’s warnings, AI-related stocks have experienced a downturn, particularly among semiconductor firms, suggesting a waning enthusiasm for ongoing capital expenditure in the sector. Major hyperscalers are projected to spend around $800 billion this year, with estimates for next year exceeding $1 trillion. However, access to capital for AI firms may not be as straightforward as it appears. For example, Meta has engaged in significant debt issuance and recently announced a new class of shares to manage financial obligations.
In light of rising costs and increasing credit default swap rates, smaller AI entities are also facing pressure. The stock of CoreWeave, for example, plummeted over 30% this month, and its credit risk metrics have surged dramatically.
Potential Risks in AI Investment Strategies
Further complicating the scenario are concerns voiced by S&P’s Global Head for Digital Infrastructure, Mark Habib, regarding the “interconnected financing structures” between larger firms and smaller entities in the AI sector. “It is safe to assume that there is more (debt) out there that we are not seeing,” he articulated, stressing the need for greater transparency in financial disclosures in the AI market.
As the landscape of AI investment continues to evolve, it remains essential for stakeholders to carefully assess the long-term feasibility and sustainability of their investments in this rapidly changing sector.
