


Understanding Financial Risk
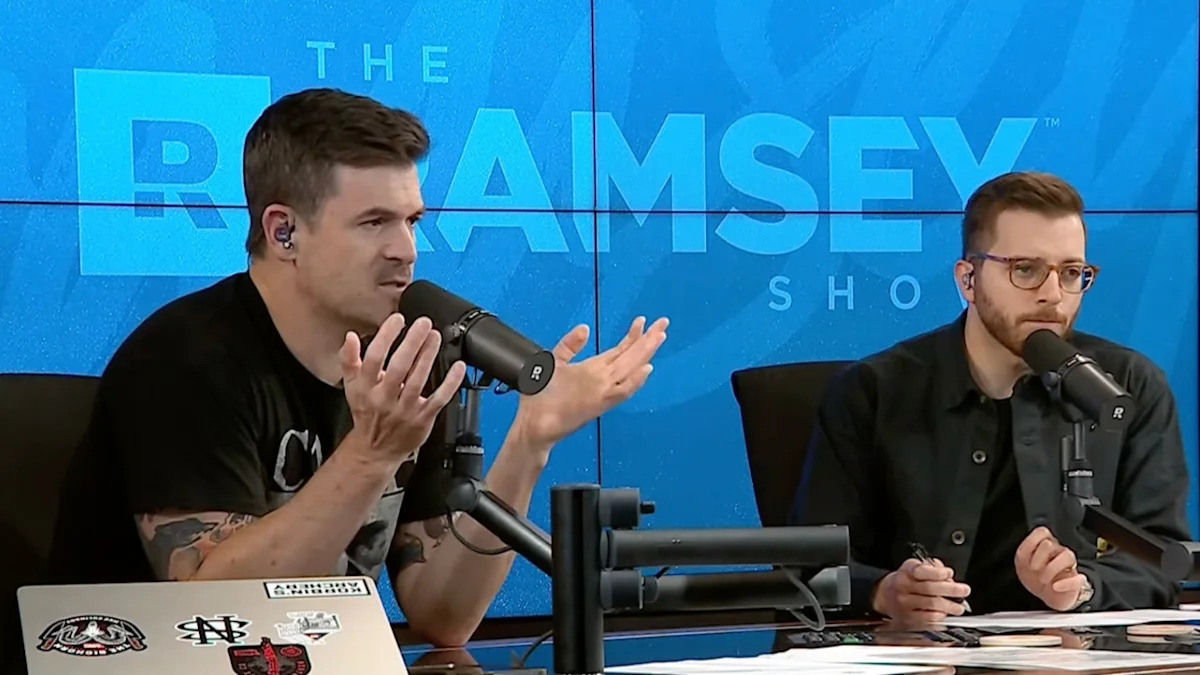
In a recent episode of The Ramsey Show, co-host George Kamel expressed concern for a viewer, Sarah, whose family’s entire net worth, approximately $600,000, was invested in cryptocurrency. Sarah mentioned that while $400,000 could eliminate their mortgage, her husband was resistant to cashing out.
The family’s financial situation included $20,000 in car loans, only $5,000 in savings, and an annual take-home income of $170,000, all while raising three children. The overwhelming concentration of wealth in one highly fluctuating asset poses significant risks.
The Dangers of Concentration in Investments
Investment professionals frequently advocate for diversification. As summarized by the U.S. government’s Investor.gov, diversification is essential to mitigate risks: “Don’t put all your eggs in one basket.” This principle is particularly crucial in the volatile cryptocurrency market, where significant losses can occur rapidly.
The Financial Industry Regulatory Authority has warned that cryptocurrencies are “risky and often extremely volatile,” with potential losses impacting the family’s savings, home equity, and future plans all at once. Kamel noted that Bitcoin’s price had plummeted by over 50% in the past year, highlighting the unpredictability of this asset.
Emergency Funds and Financial Resilience
The financial cushion of $5,000 for a family of five is minimal. According to the Federal Reserve’s Survey of Household Economics, more than 40% of adults would struggle to cover a $400 emergency expense without resorting to credit or loans. Lacking sufficient savings may lead families to sell investments at unfavorable times, highlighting the necessity for liquid assets.
Tax Implications of Selling Cryptocurrency
Additionally, Sarah’s hesitation to sell stems from the potential tax consequences. The IRS treats cryptocurrencies as property, meaning any gains or losses realized from a sale require detailed tax reporting. The timing of when the cryptocurrency was purchased affects whether it incurs long-term or short-term capital gains tax, impacting the total tax liability when they decide to sell.
Exploring Alternative Financial Strategies
Eliminating the mortgage debt could free up substantial monthly cash flow, allowing Sarah and her husband to build their savings. However, it isn’t the only option available for reducing their financial risk. In discussing their financial strategy, the Ramsey Show hosts suggested that balancing around $500,000 of their investments could not only clear existing debts but also establish a more robust emergency fund. They highlighted that even modest savings can significantly impact financial security.
Final Thoughts on Financial Security
Kamel’s reflection on Sarah’s situation serves as a critical reminder of the risks associated with concentrated investment strategies. If a downturn in the market could jeopardize home equity, savings, and retirement concurrently, it is essential to reassess and diversify one’s portfolio appropriately. Establishing an emergency fund and spreading investments across various asset classes are effective ways to mitigate such risks.
