


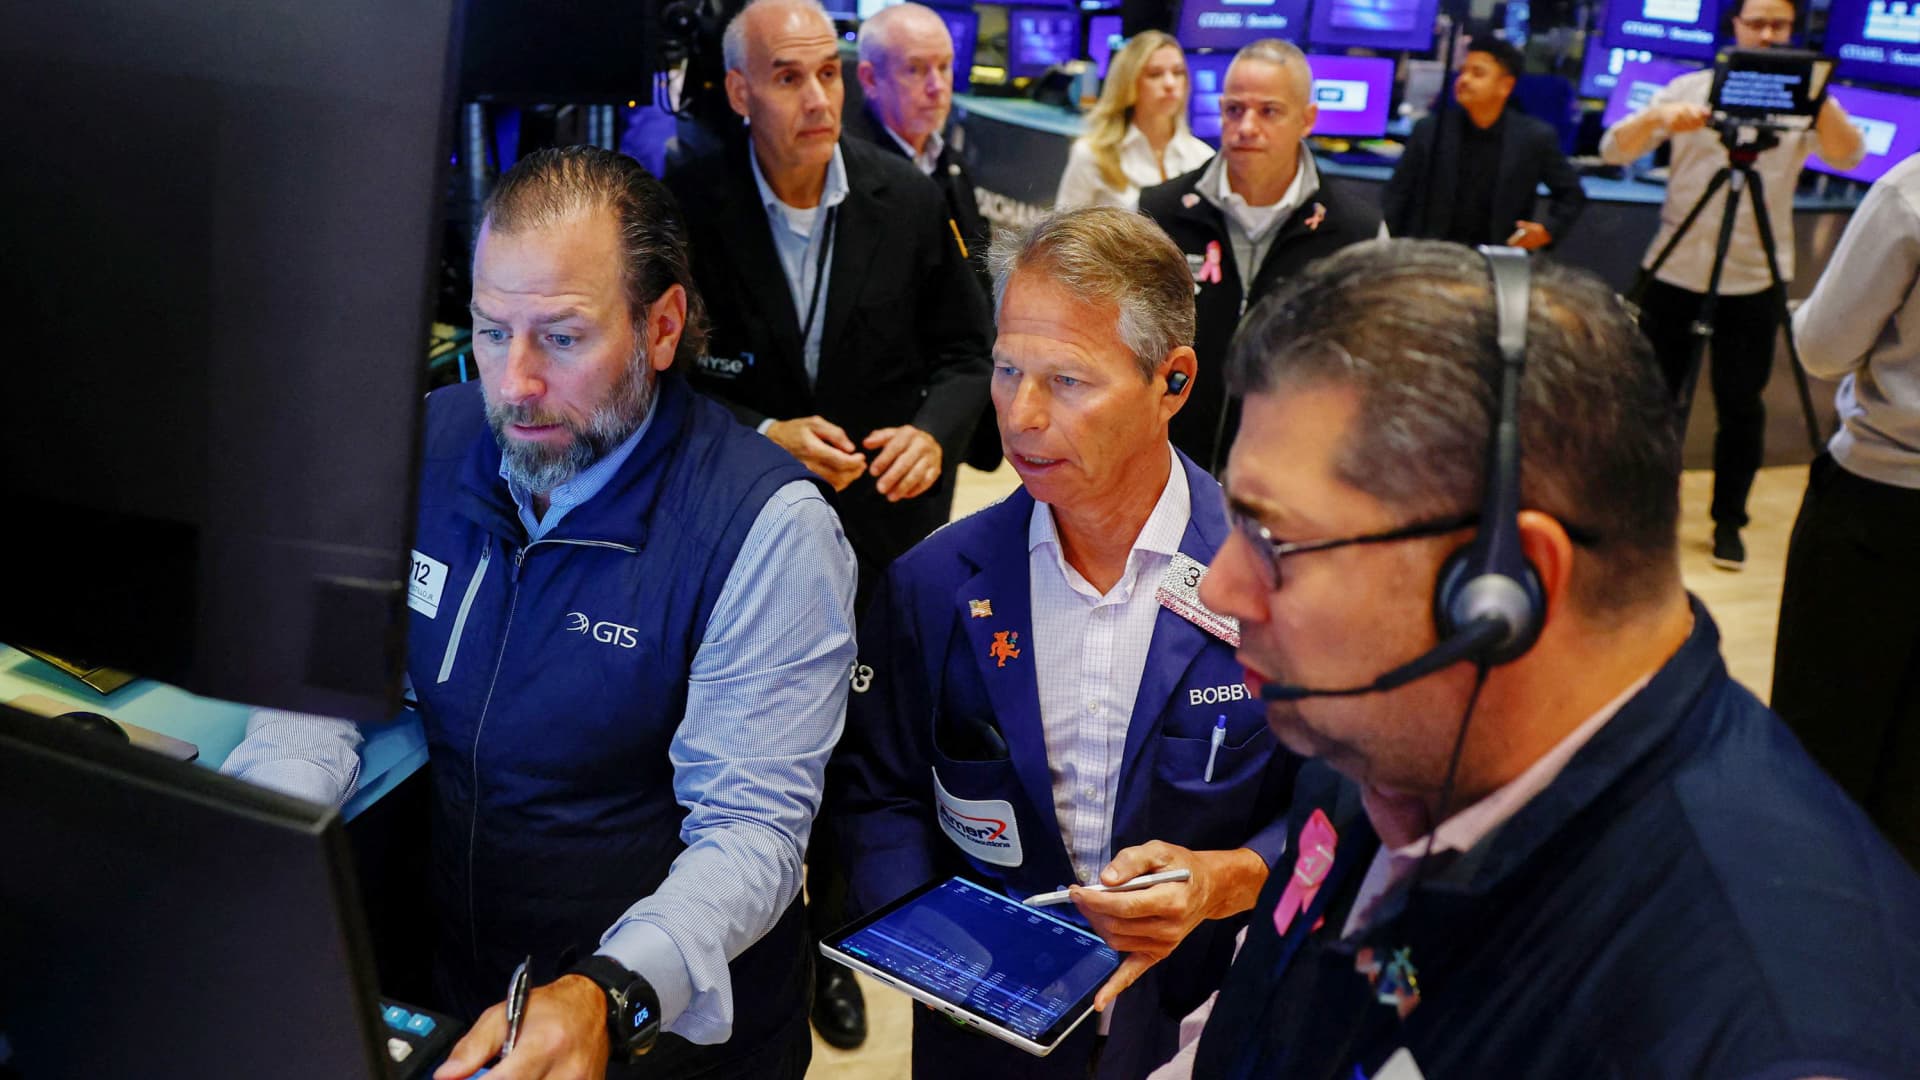
Market Update: Tech Recovery Amid Midterm Election Anticipation
On October 26, 2026, major U.S. stock indices experienced notable movements as investors cautiously re-engaged with key technology stocks following a period of pressure. The Nasdaq Composite rose by 1.1%, signaling a rebound after recent losses, while the Nasdaq-100 index increased by 0.9%, although it remains in correction territory—approximately 10% below its recent peak.
Stock Performance Overview
The S&P 500 index registered a 0.6% increase, contrasting with the Dow Jones Industrial Average, which fell by 0.2%, dropping around 100 points. This decline was largely influenced by a nearly 2% decline in shares of Apple after the company predicted disappointing margins and reported that iPad sales for the fiscal fourth quarter fell short of analyst expectations.
Sector-specific Highlights
- Chipmakers on the Rise: Stocks in the semiconductor sector performed well, with Advanced Micro Devices gaining 4% ahead of its third-quarter results, Broadcom rising over 3%, and both Micron Technology and Nvidia increasing by more than 2% each.
- Oil Market Movements: Oil prices declined, driven by speculation around potential progress in negotiations between the U.S. and Iran. Brent crude oil prices decreased by nearly 1% to about $104 per barrel, while West Texas Intermediate futures remained stable at approximately $96 per barrel.
Market Sentiment and Economic Outlook
The latest trading session’s rebound followed a downturn on Monday, where the Nasdaq experienced a drop exceeding 1%, marking a continuation of its decline over three consecutive days. Despite the recovery signs in the semiconductor sector and other industries linked to artificial intelligence, market experts suggest underlying concerns persist.
Shawn Snyder, an economic strategist at Potomac Fund Management, cautioned that “the concerns about the cost of capital and the level of debt financing necessary are going to persist for quite some time.” He did note, however, that there may be a potential for a slight downside of about 4% to 5%, although historically, markets tend to stabilize if a recession does not accompany these drawdowns.
Implications of the Midterm Elections
Attention is also focused on the U.S. midterm elections, which could reshape Congressional control starting January. Current predictions indicate nearly a 75% chance that Democrats will secure control of the Senate.
A potential Democratic sweep in both the House and Senate could exert downward pressure on the broader market, particularly targeting sectors heavily invested in artificial intelligence. Conversely, should the Republicans maintain control over the Senate, or both chambers, it might lead to short-term market gains, according to analysis from JPMorgan.
Despite uncertain outcomes, economic experts like Snyder believe that the market could still rise post-election, irrespective of the controlling party. “You’re looking at an AI trade that’s already taken a hit,” he remarked. “That, combined with the idea that the uncertainty from the midterm fades, probably argues for a relief rally no matter what.”
In conclusion, while recent trading activity indicates a cautious optimism among investors, the ongoing larger economic concerns and the impact of the upcoming elections remain focal points that could influence the market’s performance in the near future.
